Event2 min read
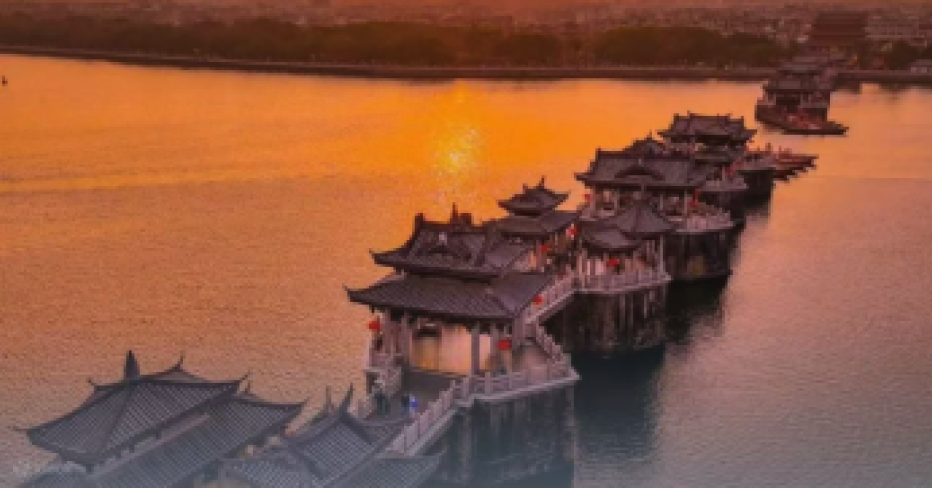
GlobalOre Members Annual Summit 2026 in Chaozhou, China
This year we’re taking the Annual Summit to Chaozhou, a city that has been trading along the Han River for more than a thousand years. It felt like the right place for a market that still runs on relationships.
From 22 to 23 October, members will meet at the Crowne Plaza Chaozhou Riverside for a day and a half of conversations, sessions and time together, away from the usual calls and chats.
What’s happening
The summit opens on Thursday with the Women in Iron Ore Gathering over lunch, followed by the Welcome Dinner in the evening.
Friday is the main day, with conference sessions held in Chinese. Our CEO opens with Built to Hold: Why Resilience is GlobalOre’s Next Product.
Speakers from GlobalOre, the China Association for Trade in Services, FLAME ASIA RESOURCES and IFCHOR GALBRAITHS will then cover:
- China’s steel industry
- Iron ore trade and investment
- The coal market outlook
- Freight strategy
A panel discussion and Q&A wraps up the morning. The afternoon is set aside for networking, because the best conversations rarely happen in a seated session.
We look forward to seeing you in Chaozhou!
Topics Iron Ore, Commodities, Global Trade
Market2 min read
Can a Pricing Regime Be Changed by the People Who Trade on It?
That's the question we kept coming back to while reading Pascale Massot's piece on iron ore market power in the latest East Asia Forum Quarterly.
Her framing is a helpful one: power in commodity markets isn't a single variable. It shows up in price levels, but also in the location of exchanges, the currency of settlement, the regulatory home of the venue, and the role of financial intermediaries. The move from negotiated annual benchmarks to index-linked pricing after 2010 redistributed all of those things — not just the number at the top of the contract.
Several things are now moving at once. Greater concentration on the buy side. Significant new supply entering the seaborne market from outside the established basins. A slow drift in average ore quality. Each of those has some bearing on how a reference price is formed and who finds it credible.
Our read: financialisation has proven very hard to reverse once liquidity, hedging and a whole class of participants have grown up around it. Reference pricing tends to shift at the margins — settlement terms, contract structure, venue — well before it shifts at the core.
Curious what others in physical and paper markets are seeing.
Topics Iron Ore, Commodities, Price Discovery, Market Structure, Steel
Trade finance2 min read
Swift's Global Currency Tracker: What It Means for Iron Ore Trade Settlement
We start this week with Swift's June 2026 Global Currency Tracker (data to May 2026). In summary:
- RMB in global payments: CNY held a 2.75% share of global payments by value in May 2026, ranking 6th worldwide, off its 2024 peak of 4.74%. USD remains dominant at 50.73%.
- RMB in trade finance tells a different story: In the MT700 (Letters of Credit) and MT400 (documentary collections) space, CNY captured a 7.00% share — the clear #2 currency behind USD's 82.50%, and ahead of EUR at 5.51%.
The takeaway: The USD remains the dominant currency for payments globally. This said, RMB's footprint in trade finance is running well ahead of its footprint in general payments. For iron ore, where China sits on the demand side of nearly every major flow, this gap is worth watching closely as an indication of the RMB internationalization macro trend as it raises a settlement design question for sales contracts.
At globalORE, we see this as reinforcing the case for platforms that support multi-currency settlement optionality from day one, rather than defaulting solely to USD-denominated LC structures. Counterparties increasingly need the flexibility to settle in the currency that best matches their trade and FX risk profile.
Are you seeing RMB-denominated LC requests increase in your own iron ore flows?
Source: Swift; Shankar T S
Topics Iron Ore, Trade Finance, Letters of Credit, Commodities Finance
Supply chain2 min read
The Black Sea Shutdown: Invisible in the Benchmark, Real for Europe
This week we are taking a break from analysing the changes in the iron ore pricing regime and focusing on the Black Sea.
The global iron ore price barely moved when Ukraine's Black Sea export corridor shut down. Zoom into Europe and the story looks completely different.
Ukraine is roughly 2% of world iron ore export value — invisible in the benchmark. But it's quietly supplied 16-18% of the EU's iron ore imports for the past several years, concentrated in Poland, Slovakia, and Czechia. Behind Canada and Brazil, but a real, concentrated dependency for the mills that rely on it.
About half of those exports moved by sea. Shipowners stopped sailing in late July after repeated strikes on commercial vessels, and Ferrexpo — Ukraine's main pellet exporter — has since suspended production entirely. It's currently filling European orders from a stockpile. According to news reports, that stockpile runs out around mid-September without new financing.
Why is this worth monitoring? Because the DR pellets feed into the green-steel programme of European mills — meaning this isn't just blast-furnace feedstock, it's an input some of Europe's decarbonization bets are built on.
Here's the interesting part: the EU just cut Ukraine's duty-free finished-steel quota by 59% under a new safeguard, while its own mills still need Ukrainian raw ore and pellets — which face no such restriction. Europe is closing the door on Ukrainian steel and leaving it open for Ukrainian ore.
No European steelmaker has said publicly that they're short and Vale reportedly commissioned its Serra Sul +20 main conveyor belt, initiating a production ramp-up at the S11D complex, to partly offset Ukrainian shortfalls in H2 2026. Worth checking back mid-September to see if that's still true.
Topics Iron Ore, Steel Industry, Europe, Supply Chain
Market2 min read
Iron Ore Pricing Is Entering a Dual-Node Era
For years, seaborne USD benchmarks have acted as the number everyone anchored to. Now we're moving into a regime where onshore RMB portside indices are just as important, and closer to what Chinese buyers actually pay. This shift has consequences for anyone who prices, hedges, or explains iron ore.
1. Two price nodes, two sets of drivers
- Seaborne USD CFR indices – driven by global supply, freight, macro risk, and international liquidity.
- RMB portside FOT indices – driven by China's inventories, steel margins, taxes, inland logistics and domestic credit conditions.
These can and do diverge once you adjust for FX, moisture, port costs and tax. What this means in practice is working off a single "iron ore price" on your slide deck or risk report risks compressing two different realities into one number.
2. Price discovery is moving closer to the end user
More transactions are settled in RMB, not just USD, and referencing portside indices and onshore futures (DCE) rather than only seaborne benchmarks in contracts. That means true price discovery for China demand is happening at the port and on local screens, not only in international indices or offshore derivatives.
If your informational universe is limited to USD CFR indices and SGX/CME screens, your view of value is incomplete. You need to at least track the portside RMB node and the basis between the two.
3. "The iron ore price" is now a basis, not a point
In a dual-node system, the key question is not "what's the iron ore price?", but "what's the spread between seaborne USD and portside RMB, and what drives it?" That spread is where:
- Policy decisions show up first.
- Inventory stress and steel margin compression become visible.
- Mispricing – and opportunity – emerges.
4. The thought-leadership challenge
The deeper conversation is: How do we build pricing, risk and strategy frameworks that accept multiple benchmarks as normal and focus on:
- The relationships between them.
- The underlying structural forces that move those relationships over time, instead of financial market movements.
Iron ore is simply an early case study in a broader trend: as major demand centers develop their own currencies, platforms and indices, price discovery will become more local – and more plural.
Topics Iron Ore, Commodities, Price Discovery, RMB, USD, Risk Management